Achieving Financial Freedom: The Ways in Which Advisers Are Able to Assist
In today's complex financial landscape, achieving financial freedom is vital than ever. With rising costs of living and an unpredictable economy, numerous individuals feel themselves overwhelmed when it comes to planning for their future. This is the point at which financial advisers step in, providing the expertise and guidance necessary to help navigate the intricacies of personal finance. Regardless of whether you are just starting your career, preparing for retirement, or managing an estate, having a knowledgeable adviser can make all the difference in reaching your financial goals.
Understanding the role of a financial adviser can frequently result in a deeper appreciation of their value. From helping you develop a realistic household budget to guiding you through investment planning, they offer tailored strategies that fit your specific situation. By having the right support, you can avoid common financial planning mistakes, develop an effective savings plan for retirement, and work towards the financial freedom that allows you to enjoy life without stress. In this article, we will discuss how advisers can assist you in realizing your financial dreams and the key considerations for selecting the right fit for your needs.
Choosing the Right Financial Advisor
Selecting the right monetary advisor is essential for achieving your monetary objectives. Start by clarifying your specific requirements and objectives. Are you seeking for support with retirement strategies, portfolio strategies, or tax-optimized techniques? Understanding what you need will assist refine your choices. Also, evaluate the adviser's qualifications and experience, as these factors can greatly influence the standard of financial advice you get.
It is also important to evaluate an advisor's consultation style and manner to financial strategy. A great adviser should be able to clarify intricate economic concepts in a way that is clear to understand. Schedule an preliminary meeting to determine whether you feel comfortable discussing your financial situation with them. Confidence and rapport are key components of a productive advisor-client partnership, as you will be disclosing private financial data and depending on them for guidance.
Lastly, be mindful of the cost structures economic advisors use. Some charge a fixed fee, while some receive fees based on the services they suggest. It’s important to choose a cost model that aligns with your desires and guarantees the advisor's incentives are in line with your optimal needs. Asking queries about their compensation model during your initial meetings will assist you make an educated decision.
Creating a Financial Strategy for Your Prospects
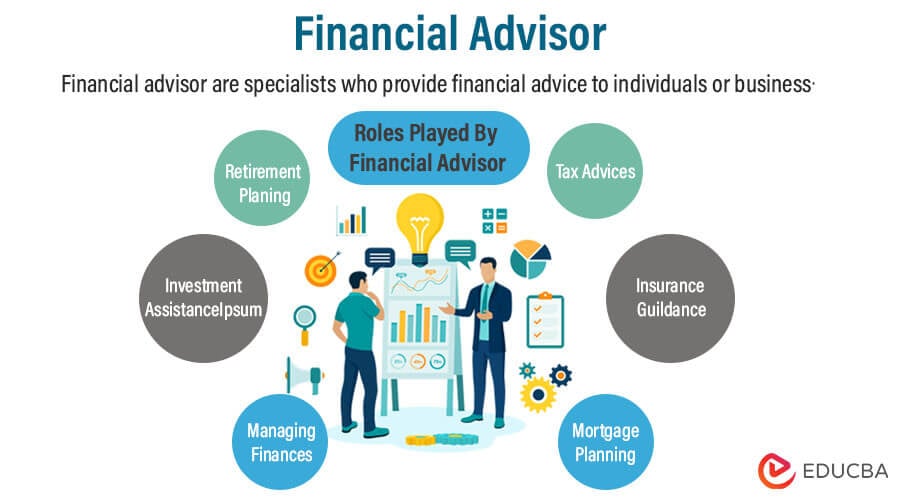
Formulating a monetary plan is essential for achieving your extended objectives and securing fiscal safety. A thorough monetary program starts with identifying your goals, whether or not it's setting aside for the future, acquiring a home, or funding your kids' schooling. By explicitly stating your targets, you can sketch particular actions to attain them and establish a schedule for when you hope to reach each goal. This focus on your individual desires will direct your monetary determinations and keep you inspired along the way.
Once your goals are defined, the following step is to assess your existing financial status. This comprises assessing your earnings, expenses, holdings, and debts. Reviewing where you stand monetarily allows you to identify shortcomings and aspects for enhancement. It also assists you grasp how much you should to stash and invest to achieve your objectives. With a clear view of your economic basis, you can create a realistic spending plan that corresponds with your priorities and supports your future strategies.
Ultimately, it's important to reassess and modify your financial program consistently. Life can shift, and so can your economic objectives. A well-organized strategy should be adaptable to respond to new conditions, such as a job transition, household expansion, or financial shifts. https://notes.medien.rwth-aachen.de/Am3wiZWURKqhimTPIh4URA , ideally with a monetary professional, allow you to make essential adjustments, keep on path to fulfill your objectives, and capitalize on chances that may appear. This forward-thinking method will assist ensure your monetary plan remains applicable and productive throughout your journey.
Frequent Financial Planning Blunders
One of the most typical financial planning mistakes people make is neglecting to set well-defined, realistic financial objectives. Without well-defined goals, it becomes challenging to create a consistent financial plan. People often set vague objectives, such as wishing to “save more” or “be better off,” yet specifying targets or deadlines. This lack of clarity can lead to confusion and ineffective strategies, ultimately obstructing one’s financial progress. It is crucial to outline concrete targets that are measurable, attainable, relevant, and deadline-driven to guarantee a targeted approach to financial planning.
A different frequent error is neglecting to build and maintain an emergency fund. Many think their income will stay steady and adequate for all unexpected expenses, but this is frequently not the case. Without an emergency fund, individuals may be forced to borrow from credit or loans during financial emergencies, leading to debt accumulation and stress. Financial advisers stress the significance of having a safety net that covers at least 3-6 months' worth of living expenses. This fund safeguards against unforeseen circumstances like job loss, medical emergencies, or urgent home repairs.
Lastly, a major blunder in financial planning is failing to regularly evaluate or change one’s financial plan. Life circumstances change, and so do financial targets and market conditions. Neglecting to revisit and adjust one’s plan can result in overlooked opportunities or an unsuitable strategy that no longer aligns with one’s current situation. Engaging with a financial adviser can assist ensure that plans stay relevant and effective over time, enabling individuals to respond to changing needs and achieve their financial objectives.